Planning Ahead Can Ease Your Family’s Burden
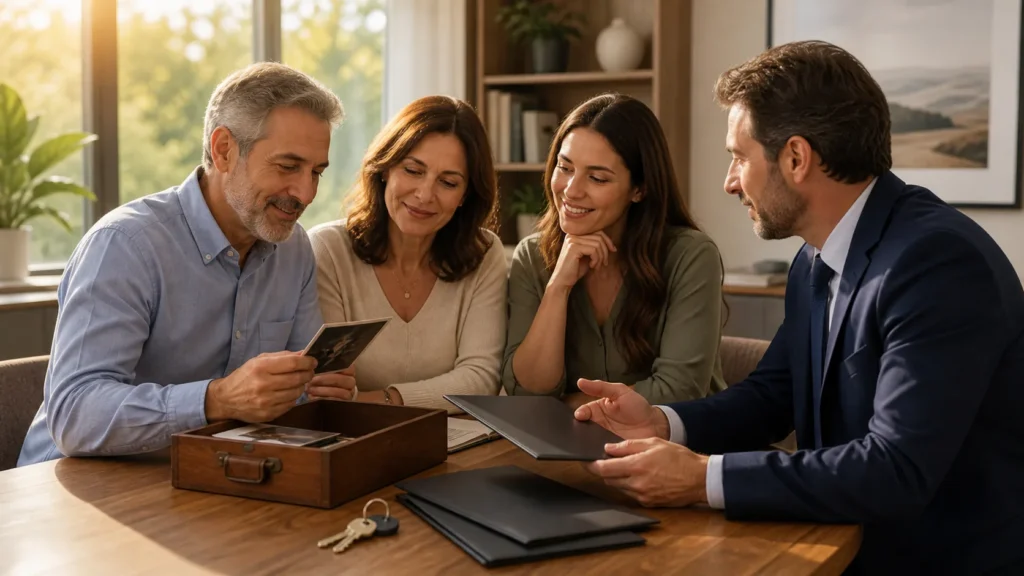
End-of-life planning gives your family clearer answers when they may be least prepared to find them. Loss brings an overwhelming amount of grief, but it can also bring immediately needed decisions about bills, paperwork, property, insurance, and final arrangements. By planning ahead, you are not expecting the worst; you are giving the people you love more time, confidence, and direction during a difficult period.
When information is hard to locate, executors and family members may be left guessing. A thoughtful plan can reduce that uncertainty, support your wishes, and help prevent misunderstandings among the people you leave behind. It is one way to care for your family long after you are gone.
Give Your Executor Clear Direction
An executor can also be called a personal representative. This person may have a long list of responsibilities after a death, including finding the will, securing assets, communicating with beneficiaries, paying debts, managing tax filings, and distributing the estate.
That role can feel overwhelming in the best organized scenarios and is amplified tenfold when there is little information available to work from. A current will gives your executor a clearer starting point and lets you name the person you trust to handle the duties that follow. It can also share your wishes for how your estate is to be handled and outline guardianship preferences for minor children.
Without a valid will, intestacy rules will determine how an estate is distributed. Those rules may not reflect the relationships, priorities, or personal wishes that matter most to you. It can distribute assets in incorrect ways or amounts, lock up funds until children reach adulthood, and can be severely costly if the family tries to battle the rules.
We often encourage families to look at their full picture when reviewing a will, including:
- Changes in family relationships or marital status
- Property, savings, insurance, or business interests
- Children or grandchildren who may depend on you
- The person named as executor and whether they are still able to serve
A financial planner can help you consider how your financial picture and legacy goals connect. A lawyer can prepare or review legal documents to help ensure they reflect your wishes and provincial requirements.
Keep Important Documents Within Reach
A well-organized record of information can save your family from searching through drawers, emails, and old files during an emotional time. The goal is not to make private details available to everyone. It is to ensure the right people know where to find what they need.
Your records may include the location of your will, insurance policies, account information, property records, business documents, and contact details for your lawyer, accountant, and planning professionals. You may also wish to record funeral, burial, or memorial preferences so your family does not have to make every choice without guidance.
It also helps to understand that some documents apply while you are alive but unable to make decisions. An enduring power of attorney can address financial and property decisions if you lose capacity. A personal directive can communicate preferences about personal and health-related decisions.
A secure information record may include:
- The location of legal documents and insurance policies
- Bank, investment, property, and business account details
- Digital access information stored safely
- Contact information for key professional supports
- Personal wishes for final arrangements
It can be helpful to review who knows where these records are kept. A trusted executor, attorney, or family member does not need every password or financial detail today, but it can be helpful for them to know how to access the information when it is needed.
Review Beneficiary Choices as Life Changes
Not every asset is handled through your will. Life insurance policies, registered plans, and certain accounts may pass directly to a named beneficiary. This can affect how quickly money becomes available and how the rest of the estate is administered.
Beneficiary designations deserve regular attention because life rarely stays still. Marriage, separation, divorce, the birth of a child, a death in the family, or a major change in your financial situation can all affect whether a designation still makes sense.
Outdated choices can lead to unexpected results and difficult conversations for survivors. For example, a designation made years ago may not match your current family structure or the legacy you intended to leave.
As part of broader planning discussions, we help clients identify questions around:
- Life insurance and the needs of surviving family members
- Registered accounts and named beneficiaries
- Charitable intentions and gifts to loved ones
- Estate liquidity for taxes, debts, and immediate expenses
A financial planner can help bring these questions together with your overall plans for wealth, health, insurance, and legacy. Legal and tax professionals can then provide guidance on the documents and tax matters involved.
Business Owners Need a Plan Beyond Personal Assets
For business owners, end-of-life planning includes more than personal accounts and property. Your family, employees, partners, and customers may all be affected if no one knows who can make decisions on what should happen next.
Succession planning can create a clearer path for ownership, management responsibilities, and the future of the business. It can help separate personal estate goals from the practical needs of keeping the business operating.
Several pieces may need to work together, including shareholder agreements, insurance arrangements, tax considerations, business records, and personal estate documents. If those pieces do not align, your family may face added pressure at a time when they are already coping with loss or illness.
In our conversations with business owners, we look at how business continuity fits within the larger family plan. This broader view can help reveal questions that may otherwise stay unnoticed until someone needs answers quickly.
Start the Conversation Before Your Family Needs Answers
End-of-life planning is not a one-time task to place in a drawer and forget. Family changes, new assets, health concerns, business developments, and major life milestones can all be reasons to revisit the conversations, documents and decisions that shape your plan.
A thoughtful plan cannot remove grief, but it can reduce avoidable confusion and stress. Start with the questions your family may one day ask: Who is responsible? Where are the documents? What wishes have been shared? Clear answers can leave your loved ones with more space to support one another.
Bring Your Legacy Plan Into Focus
At Statera Financial Planners, we help families connect the financial details of their legacy with the people and priorities that matter most. Working with a financial planner can help you consider how your broader financial plan supports the wishes you want to leave behind. When you are ready to discuss your planning needs, contact us for a thoughtful conversation.