A health shock can hit fast. One moment life is going on as normal, the next you are in an ER, talking to doctors and specialists, trying to call family, and wondering how the bills will get paid while taking time off from work. Those first 96 hours are packed with big medical, emotional, and money decisions, often before anyone has had time to think.
This guide walks through what usually matters most, financially, in those early days, from keeping cash moving to filing claims. This blog explains how advance financial planning can be part of your support system so money stress does not add to an already hard week.
Hour 0-24:
On the first day, the goal is simple: keep things as calm as possible. Focus on the medical conversations at hand, call the important family members you wish to be with you, and understand what steps are coming next in your health journey.
Hour 24-48: Stabilising Cash Flow and Essential Bills
Once the first day has passed and the medical situation is a bit clearer, it’s important to know that you do not need to have a full structure organized for everything. You just need to know where your money is, how to access it, and which payments are most important to keep up when the bills come due.
For many families, money priorities might include:
- Knowing where everyday cash sits, for example, chequing, savings, or a business account.
- Confirming who can access accounts for the person who is hospitalized or in medical personnel care.
- Identifying key bills, like rent or mortgage, utilities, insurance, and phone. Knowing what is automated and what needs manual handling.
- Putting off non-urgent spending decisions for a later, clearer moment.
Bill automation is a great way to support you during a crisis. Pre-set automatic payments for core bills and alerts for low balances, or unusual transactions, mean fewer concerns at 2 a.m. and ensuring you or a caregiver won’t need to remember every due date or log in to every account under stress.
Many people are also business owners, contractors, or farmers. If you are suddenly not available, it can be useful to prepare in advance:
- Which staff or management personnel can take over the key day to day responsibilities, working with them to identify which business payments are most critical so operations stay stable and avoid disruption.
- Confirm the right individuals have signing power on business accounts, should you be unavailable.
- How payroll, rent, and key supplier payments are normally handled, and confirm which can be automated versus requiring manual input.
A business agreement prepared in advance can map this out so that from day one of a crisis there is a step by step guide and instructions in play to avoid any guessing.
Hour 48-72: Organising Documents and Caregiver Roles
The next focus is documents and roles. This is about making it easier for people to help, without everyone talking over each other about what is best for you.
Key documents that may be needed to enact and review in the first few days include:
- Health care directives or personal directives
- Enduring power of attorney
- Insurance policy details, like group benefits and any private coverage, contacting your advisors to see what is available or required to complete in your particular circumstance.
- A basic list of accounts, including banks, pensions, and investment firms
- A secure way to share passwords or digital access, if appropriate. It doesn’t need to be fancy. Even a simple folder or a secure digital file, updated once a year, can save family members from hunting through drawers during a stressful night.
Clear roles alongside you can also make a big difference. Many families find it helpful to name:
- The personal directive as the “primary medical caregiver”, who talks to doctors with you and tracks health updates
- The Power or attorney as the initial communication line to banks, HR, and insurers when it is deemed that you can’t.
- A general communicator, who keeps siblings, in-laws, and close friends in the loop who are not to be visiting during this time.
These roles can be shared, but having one main person in each spot often keeps things smoother. This can reduce misunderstandings, especially when there are strong opinions in a family or in a small business partnership. People know who is doing what, so there is more space for support and less room for conflict.
A well-prepared financial plan can act as a calm outside support at this stage. When the bigger picture has already been thought through and documented, it becomes easier to:
- Gather financial information quickly
- Sort tasks into “now” and “later” so no one feels buried
- Notice time-sensitive items, like payment deadlines or claim windows
The goal is not to dictate exactly what a family must do, rather to keep finances organised so health decisions can stay front and centre.
Hour 72-96: Filing Claims and Supporting Income
By day three or four, the focus often shifts to income. If someone cannot work for a while, the questions becomes what options exist to ensure incoming money continues:
Common sources can include:
- Group benefit plans through work
- Private disability or critical illness insurance coverage
- Government programs, such as Employment Insurance sickness benefits
- Short-term leave options or flexible work arrangements
Before contacting any insurer or HR department, some people find it helpful to build a simple “claim package” with:
- Policy numbers and benefit plan details
- A clear list of key dates, like the date of the health event and hospital visits
- Names and contact details for HR or plan administrators
- Notes from doctors or discharge summaries, if available
- A log of every call and email, with dates and what was discussed
This kind of record can reduce delays and confusion. When claims are filed, there are often follow-up questions. Having everything written down makes it easier to answer and share updates with the rest of the family or business partners.
Timelines will vary by plan and provider, but usually there is some waiting involved. That is where advance planning can help. In calmer times, it may be useful to review:
- What coverage you have today and where the gaps may be
- Waiting periods for different types of benefits
- How emergency savings, benefits, and insurance could work together if income stops for a while
When this work is done ahead of time, day four of a health crisis is more about following a known path than scrambling to understand a pile of paperwork.
Simple Decision Checklists for an Overwhelming Week
In a hard week, even small choices can feel heavy. One helpful idea is to create “pre-made instructions” in the form of short checklists that your future self and your family can lean on.
Some practical examples that you may include are:
- Who to call first
- Who handles the needs of kids, pets, or other dependent individuals
- Who can check in on property
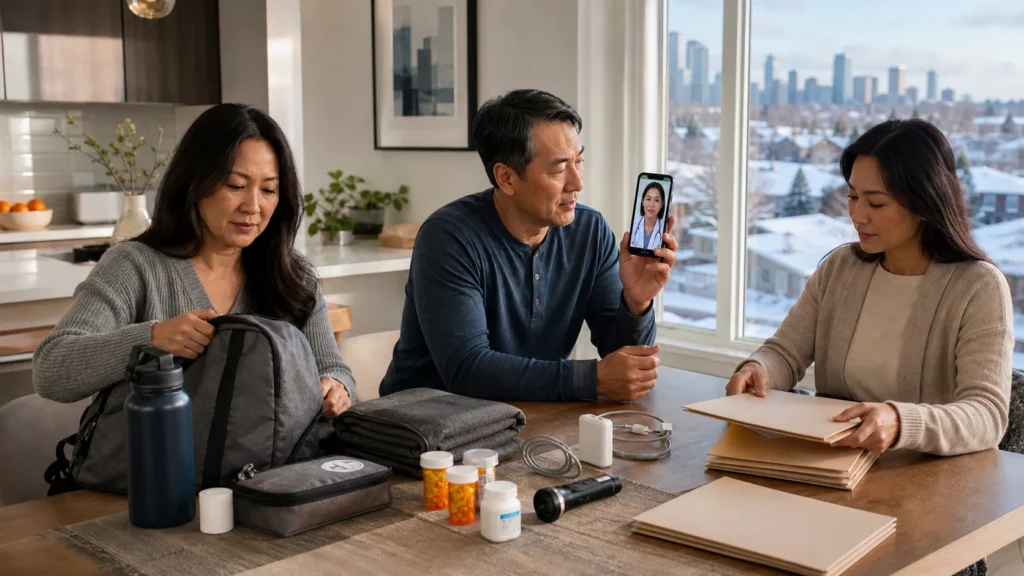
- What to pack for a hospital stay
- Key bills to review, which accounts to access,
- Subscriptions that can pause
These lists do not need to be perfect. They just need to be clear enough that someone tired and worried can follow them without starting from scratch.
Thoughtful checklists can support better health and legacy outcomes. Less scrambling often means fewer mistakes, more time for treatment decisions, and more space for meaningful family conversations.
Working with a planning professional ahead of time can help shape these lists around your own values and situation. That might include cultural traditions, blended families, complex business structures, or caring for aging parents as well as children.
Build Your Family’s Emergency Game Plan Before You Need It
This playbook is a starting point. Every family has its own mix of communication, money, work, health, and legacy goals. The next step is turning broad ideas into a simple written game plan that fits your life.
Quiet pockets of time are often best for this kind of work, so that you have a clear mind and less distraction when preparing. It can be a natural moment to review insurance, check that powers of attorney and wills are current, and confirm that online access and bill automation work the way you expect.
At Statera Financial Planners, we see wealth, health, and legacy as deeply connected. As independent financial planners, we work alongside legal and tax professionals so families and business owners can build a well-rounded emergency approach. You cannot control when a health shock arrives, but you can control how prepared you are so those first 96 hours are guided by a plan, not panic.
Take The Next Step Toward Confident Financial Decisions
If you are ready to get clear on your money and long-term goals, we invite you to learn how to choose the right independent financial advisor for your needs. At Statera Financial Planners, we take the time to understand your situation and build a plan that fits your life, not someone else’s template. When you are prepared to talk about your priorities and questions, reach out and contact us to schedule a conversation.